As we move through the second quarter of 2026, the housing market continues to evolve in ways that few could have predicted just a few years ago. If you are currently navigating the world of homeownership: whether you are looking to purchase your first property, build a custom home, or refinance an existing mortgage: the question on your mind is likely the same: “Where are mortgage rates headed, and how do I secure the best deal?”
At Inkrote Lending Solutions, we believe that clarity is the foundation of confidence. Navigating a home loan shouldn’t feel like a guessing game. Today, we’re pulling back the curtain on the 2026 rate environment, explaining the factors that drive these fluctuations, and sharing expert strategies from Jasmyne Inkrote to help you make the best financial decisions for your family.
The 2026 Mortgage Rate Landscape: A New Normal
For much of early 2026, we have seen mortgage rates settle into what many economists are calling the “new normal.” After the volatility of 2024 and 2025, the market has stabilized, but it remains sensitive to global events and domestic economic data.
Currently, the 30-year fixed-rate mortgage is hovering in the mid-6% range, typically between 6.2% and 6.5%. While this is a far cry from the historic lows of the early 2020s, it represents a significant improvement from the peaks seen during the height of the inflation battles. For you as a buyer or homeowner, this means that while the “wait and see” approach might have worked in the past, the current market rewards those who are prepared and proactive.
What is Driving Your Home Loan Rates Today?
Understanding why your home loan rate is what it is requires looking at a few moving parts. It isn’t just one factor; it’s a symphony of economic signals.
1. The Federal Reserve and Inflation
While the Federal Reserve does not directly set mortgage rates, their influence is undeniable. Throughout late 2025 and early 2026, the Fed has balanced a cooling labor market with a commitment to bringing inflation down to its 2% target. When the Fed signals a potential cut in the federal funds rate, mortgage lenders often adjust their pricing in anticipation.
2. The 10-Year Treasury Yield
If you want a “weather vane” for mortgage rates, look at the 10-year Treasury yield. Historically, there is a strong correlation between these two. In May 2026, we’ve seen yields fluctuate due to shifting investor sentiment. When yields go up, mortgage rates typically follow.
3. Geopolitical Stability and Energy Costs
In the current global climate, events abroad can hit close to home. Recent tensions and conflicts have led to spikes in oil prices, crossing the $100 per barrel mark at several points this year. These spikes fuel inflation concerns, which in turn puts upward pressure on rates. Staying informed about these global trends is part of how we help you time your rate lock effectively.
Expert Guidance: A Message from Jasmyne Inkrote
In a market that can change with a single news headline, having a dedicated specialist in your corner is essential. Jasmyne Inkrote, the owner of Inkrote Lending Solutions, prides herself on providing more than just a loan: she provides a roadmap.
“My goal is always to move you from uncertainty to ‘clear to close,’” says Jasmyne. “In 2026, we are seeing that the most successful clients are the ones who focus on their long-term financial health rather than trying to perfectly time a bottom that may never come. We focus on personalized financial advice that looks at your total budget, your family’s goals, and the unique value of the home you’re pursuing.”
Jasmyne’s approach is high-touch and service-oriented. Whether you are a first-time buyer or looking to build your dream home from the ground up, she takes the time to explain every option, from conventional fixed-rate loans to adjustable-rate mortgages (ARMs) that might offer more flexibility in the current environment.
Strategies for Securing the Best Rate in 2026
You don’t have to be at the mercy of the market. There are specific steps you can take to ensure you get the most competitive home loan terms available.
- Improve Your Credit Profile: In 2026, the gap between “good” and “excellent” credit can mean a significant difference in your monthly payment. Even a 20-point boost can save you thousands over the life of your loan.
- Consider a Short-Term ARM: If you plan on moving or refinancing within 5 to 7 years, an Adjustable-Rate Mortgage might offer a lower initial rate compared to a traditional 30-year fixed loan.
- Watch the “Lock” Window: Rate volatility means that a “good” rate today might be gone tomorrow. When you find a rate that fits your budget and helps you achieve your goal, work with Jasmyne to lock it in quickly.
- Use Professional Tools: Don’t rely on back-of-the-napkin math. Use the loan tools and calculators available on our website to get accurate, real-time projections of your potential payments.
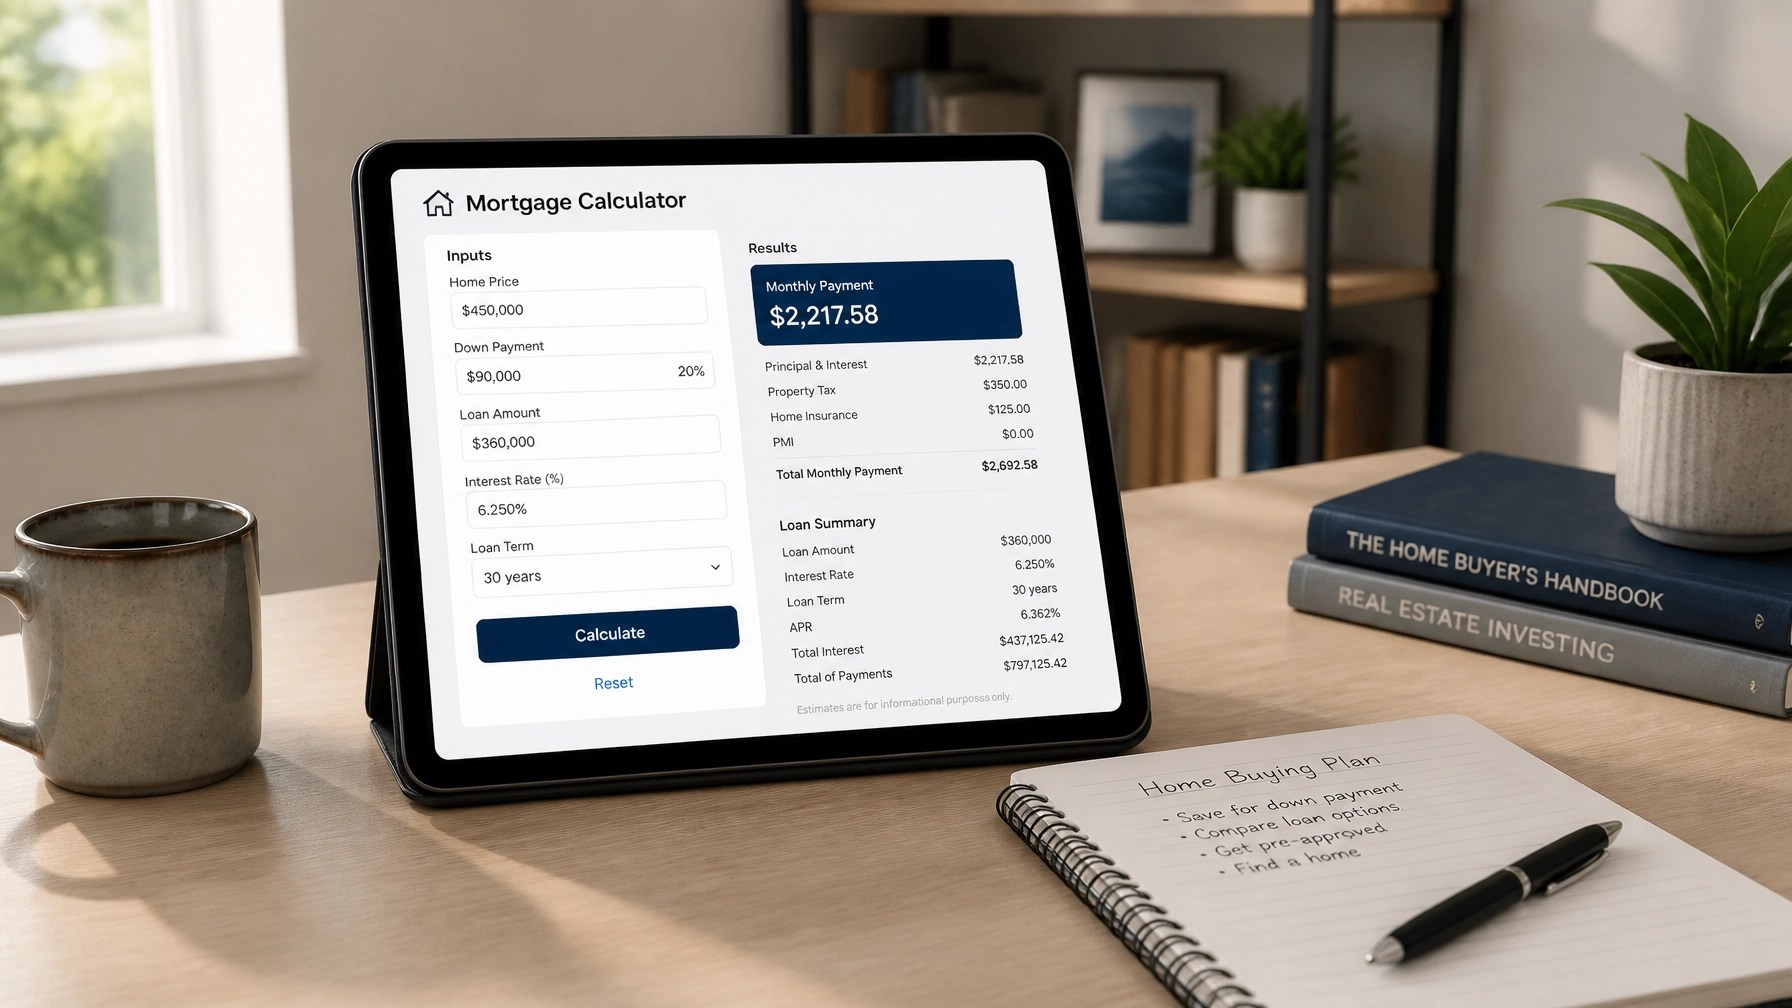
Preview
The “Lock-In” Effect and Inventory
One unique challenge of the 2026 market is the “lock-in effect.” Many homeowners are currently sitting on older mortgages with rates significantly lower than today’s averages. This has kept inventory tight, as many people are hesitant to sell and take on a new, higher-rate home loan.
However, we are starting to see this thaw. As rates have eased into the 6% range, more families are deciding that the benefits of a new home: more space, a better school district, or a shorter commute: outweigh the cost of a slightly higher rate. If you are waiting for rates to hit 3% again before you move, you might be waiting a long time. The current environment is about finding the balance between a manageable rate and the lifestyle you want for your family today.
Why Choose Inkrote Lending Solutions?
At Inkrote Lending Solutions powered by Edge Home Finance, LLC, we combine the efficiency of modern technology with the personalized care of a boutique firm. Our online application process is designed to be fast and easy, allowing you to get the information you need without the traditional headache of bank paperwork.
But beyond the tech, it’s about the relationship. We understand that a mortgage isn’t just a financial transaction; it’s the key to your future. We are committed to being your expert guide, helping you navigate shifting market conditions and complex mortgage programs with ease.
Ready to Take the Next Step?
Whether you are just starting to browse listings or you are ready to start building your new home, we are here to help. Don’t let the headlines overwhelm you. Let’s sit down and look at the numbers together.
Your ultimate goal is our primary objective. Let’s find the right home loan for your situation.
- Visit us online: urclear2close.com
- Start your application today: Experience our fast and easy online process.
- Get personalized advice: Reach out to Jasmyne Inkrote directly for a consultation tailored to your financial needs.
In 2026, the key to success is information and action. We look forward to helping you unlock the door to your next home.
Leave a Reply